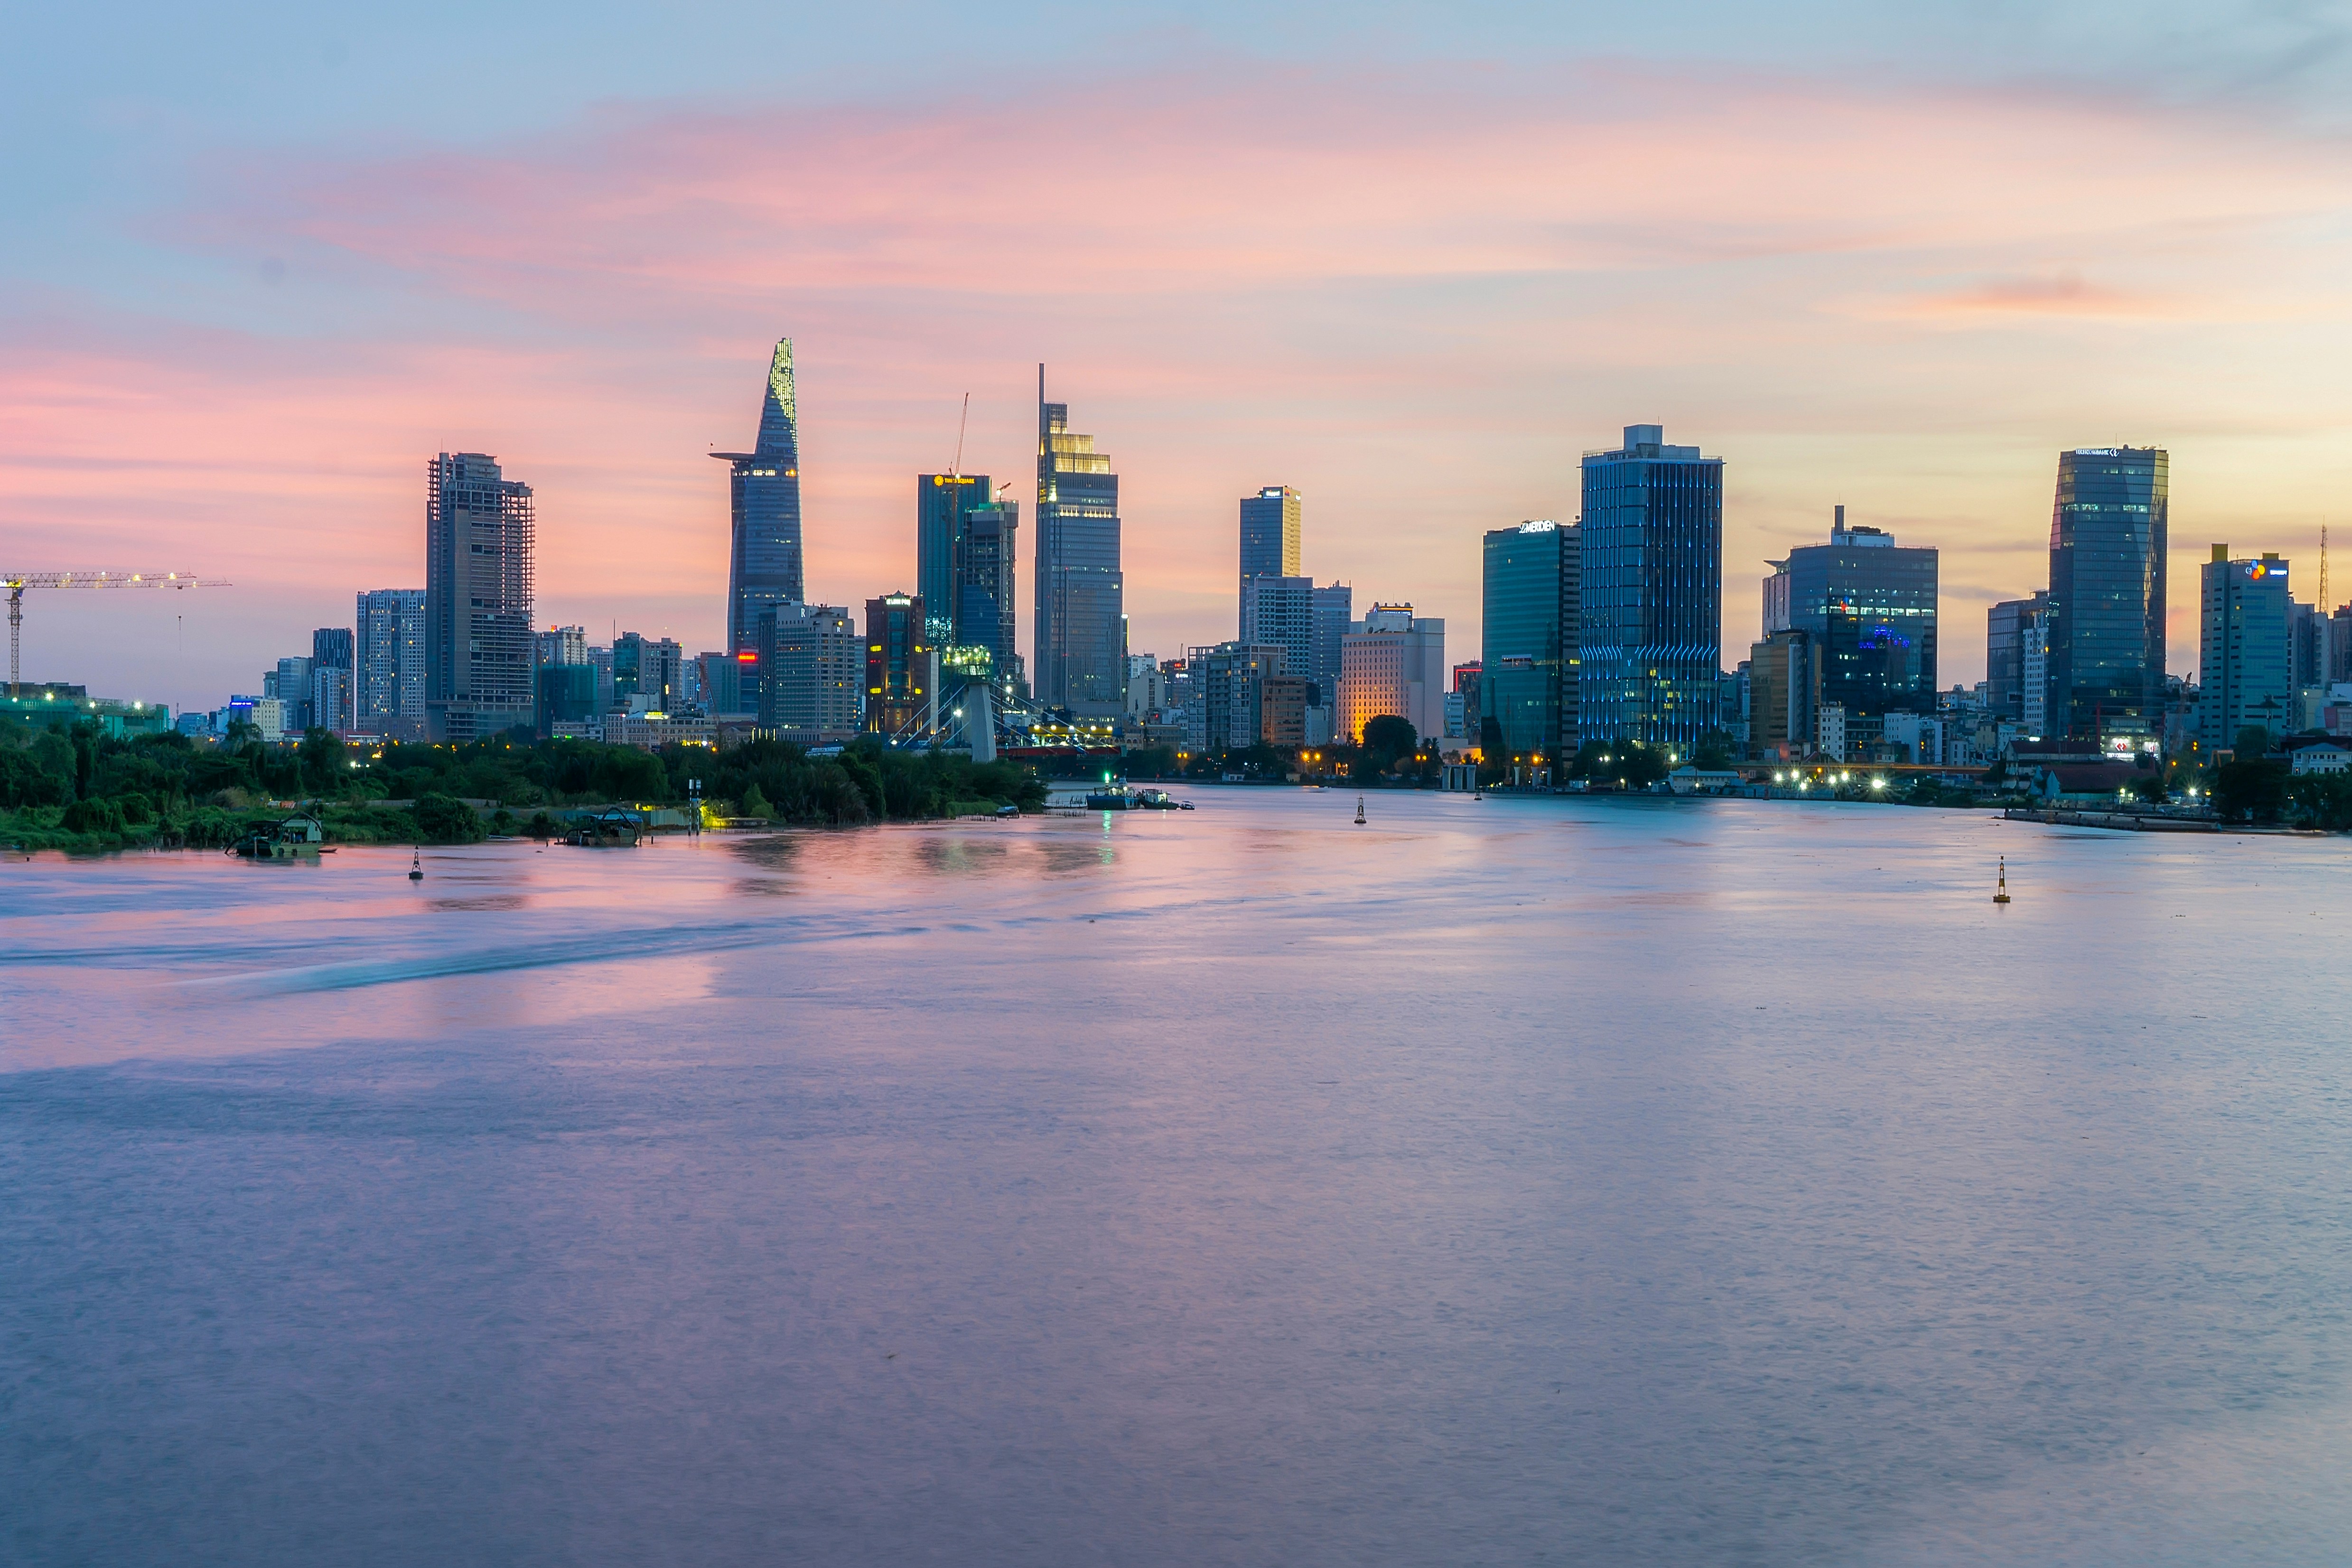
In 2026, Vietnam is emerging as a strategic alternative to saturated markets. Driven by robust growth (5 to 7%) and real estate FDI up 18.8%, the country is attracting institutional capital. Between 8% rental yields in Da Nang and a specific legal framework (50-year lease), here is how to navigate a complex but promising market.
A country moving from investors' radar into their portfolios
Ten years ago, Vietnam was still seen as a pioneer market, reserved for the most adventurous profiles and entrepreneurs looking to capture Asian growth before everyone else. Those days are over. In April 2026, at a seminar in Ho Chi Minh City bringing together major international real estate advisers, Savills, Cushman & Wakefield and VinaCapital painted a consistent picture: Vietnam is becoming one of the most closely watched destinations for international capital seeking both yield and security.
This repositioning is not a communication effect. It rests on measurable economic fundamentals, a continuous path of regulatory reform and a particular geopolitical moment that makes some alternative markets more attractive than ever.
What the fundamentals say
Economic growth that holds up in a difficult global environment
Vietnam's GDP is expected to keep growing by 5 to 7% from 2026, an attractive level at a time when many large economies are slowing down. The country is moving from a subcontracting economy to a model that attracts higher-quality foreign direct investment, while strengthening its domestic supply chains. Major infrastructure projects such as Long Thanh International Airport and the national motorway network are boosting not only economic activity but also, directly, the property market.
Macroeconomic stability, strong long-term growth potential and Vietnam's growing role in global supply chains should allow it to keep attracting large foreign direct investment flows in 2026.
In 2024, approved foreign direct investment in real estate reached 6.31 billion dollars, 16.5% of total inbound FDI and an increase of 18.8% on the previous year. Real estate has become the second largest recipient of FDI, just behind manufacturing. It is no longer a niche market for foreign investors. It is a segment attracting serious institutional capital.
Political stability as a competitive advantage
Troy Griffiths, Deputy Managing Director of Savills Vietnam, stressed at the seminar that political stability is the most decisive factor giving Vietnam an edge over regional neighbours such as Thailand, Indonesia and Malaysia. In a world shaped by geopolitical uncertainty, capital tends to flow towards markets able to preserve value and minimise risk.
That argument deserves context. In 2026, while Dubai is going through a phase of direct geopolitical tension, some emerging markets are under monetary pressure and Europe is managing its own budgetary weaknesses, Vietnamese stability looks like a real relative advantage to a number of investors. It is not Swiss stability. It is the stability of a fast-growing country with predictable governance, not directly exposed to current regional conflicts.
The property market: what works and what to know before investing
The segments attracting capital
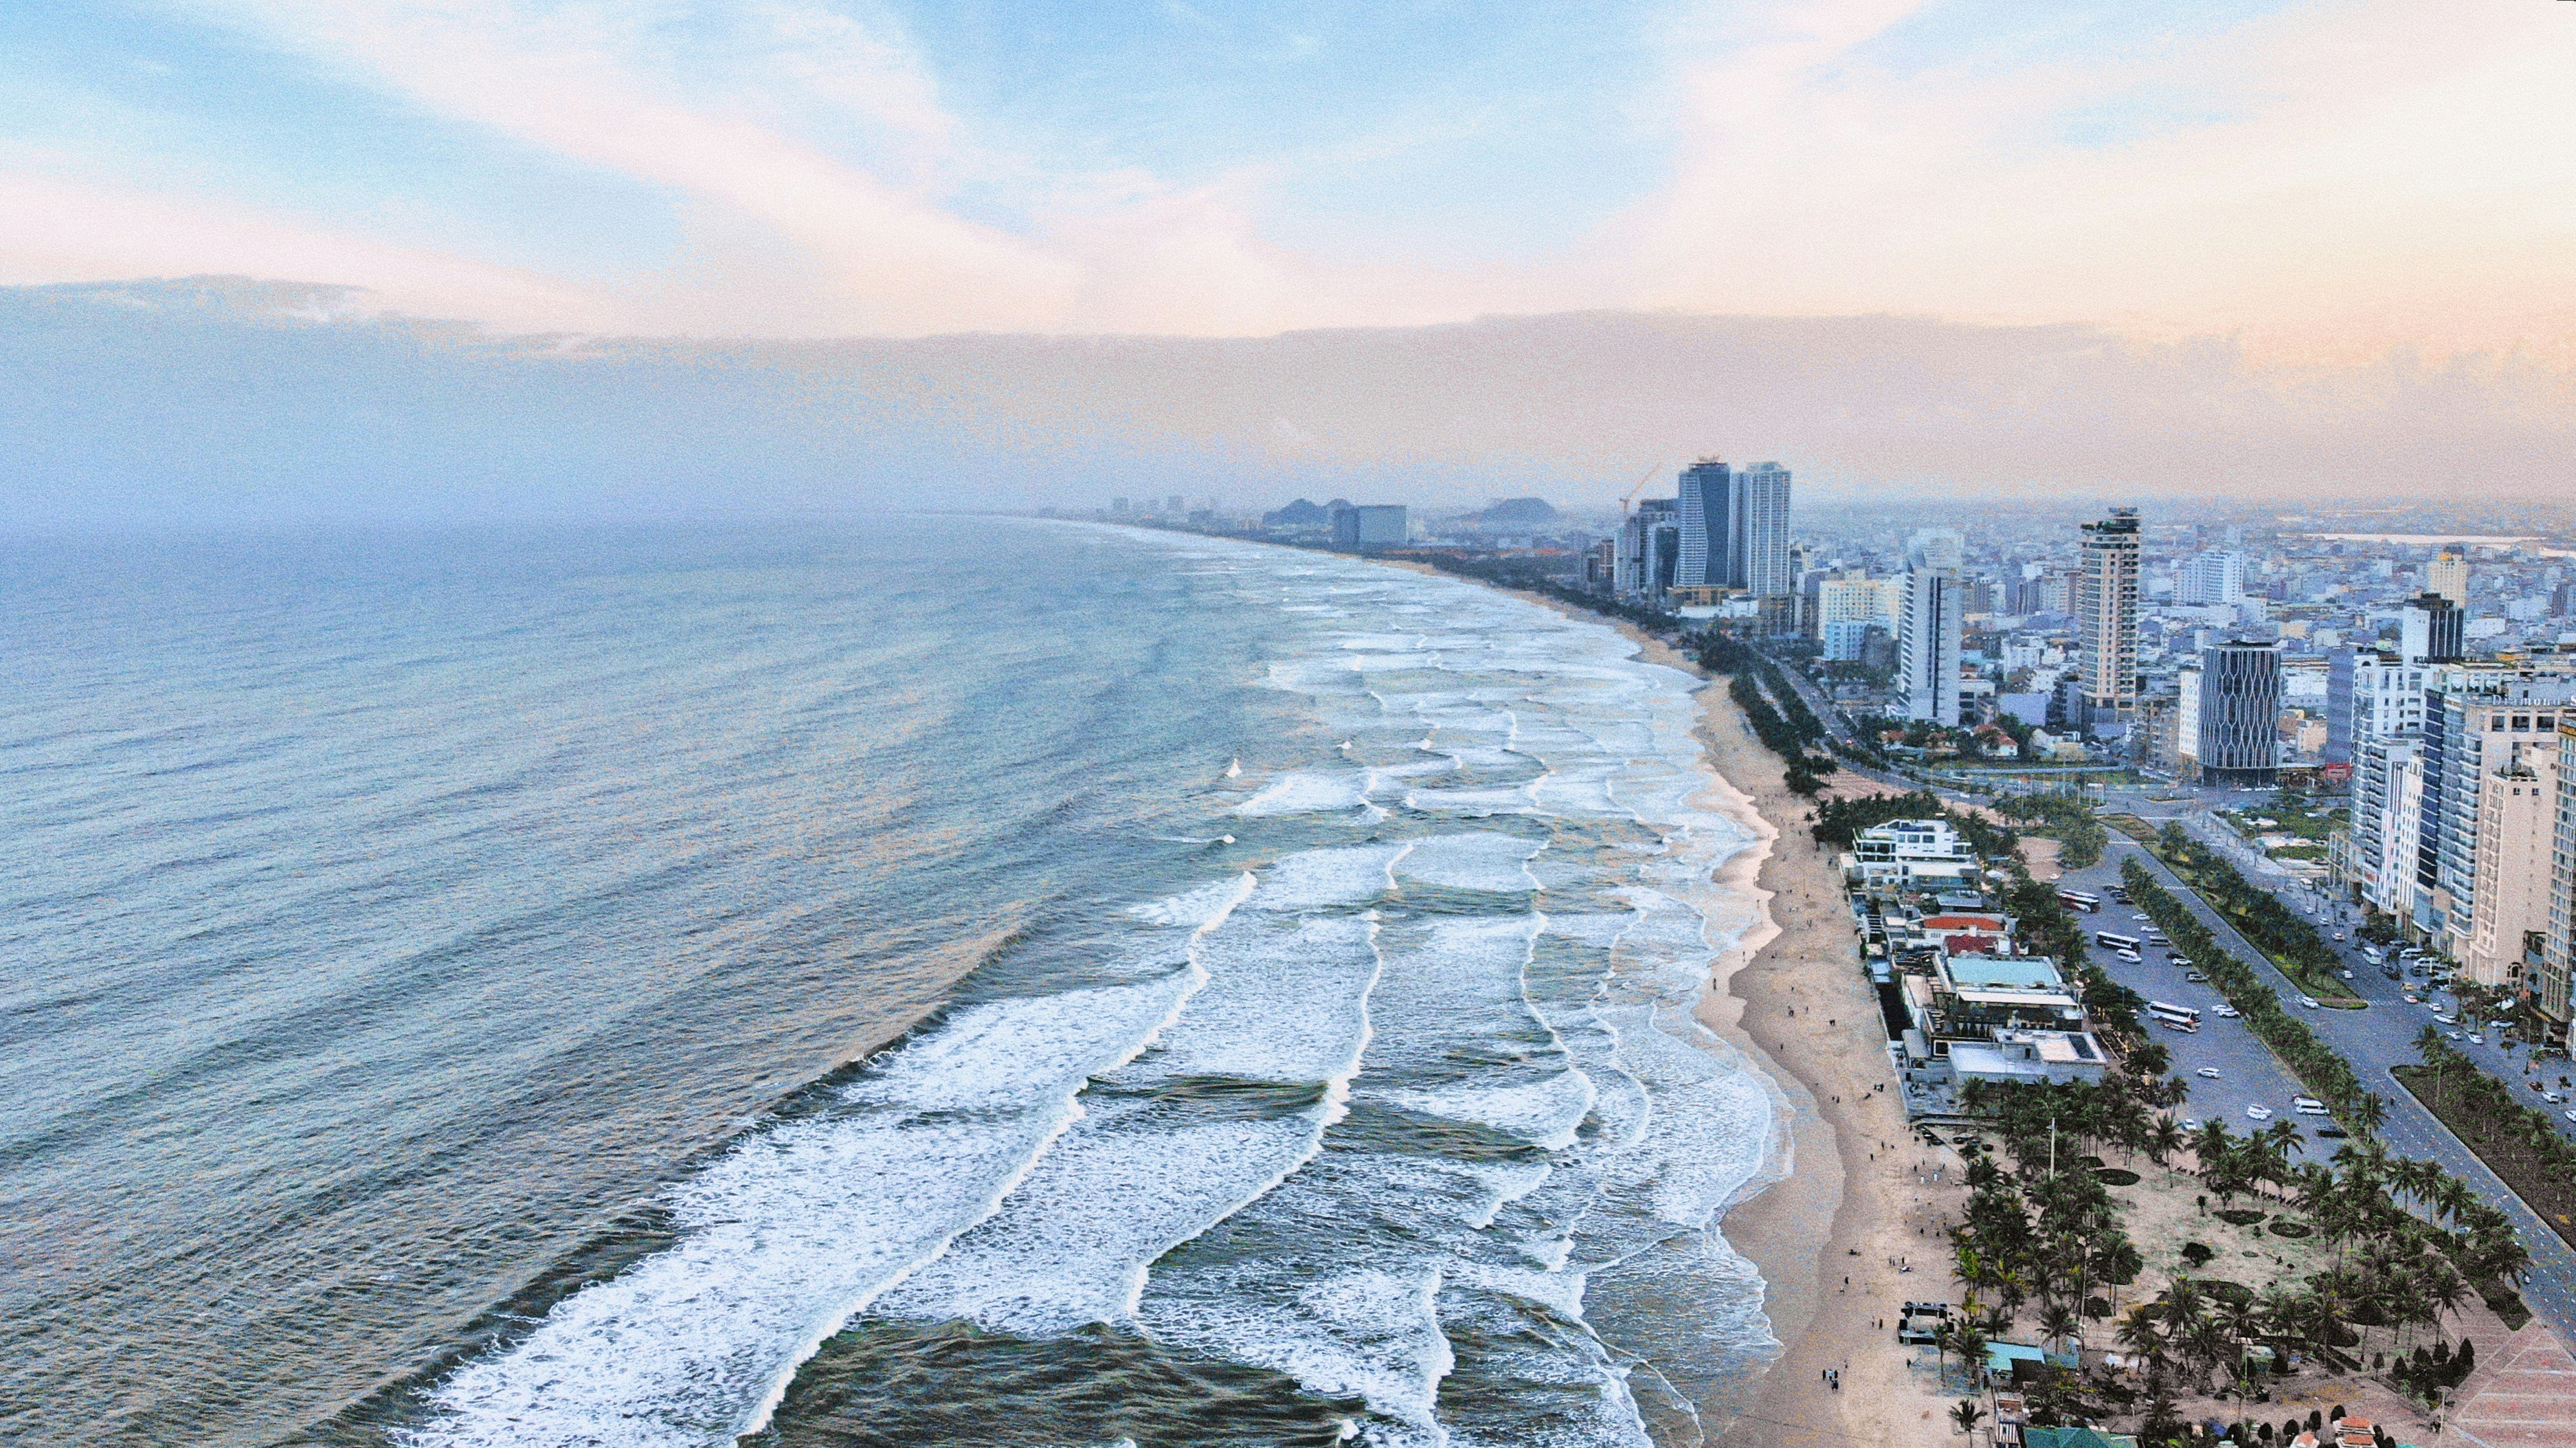
According to Do Tri Hieu of VinaCapital, coastal real estate stands out as a high-potential segment. With more than 21 million international visitors in 2025 and plenty of room for tourism growth, Vietnam has the potential to develop global destinations comparable to the Dubai or Singapore models.
Cities such as Da Nang, Nha Trang and Phu Quoc capture most of this interest. In Da Nang, demand for modern apartments is strong, while Nha Trang and Phu Quoc attract investors looking for villas and holiday homes. Rental yields in these areas have reached an average of 8% with occupancy rates around 75%.
Ho Chi Minh City and Hanoi remain the deepest and most liquid markets. According to Savills, Ho Chi Minh City offers average gross rental yields of 5.8%, while Hanoi shows 7.8%. Districts linked to new metro lines and ring roads are seeing the sharpest increases, with strong demand from the rising middle class and expatriates.
The underlying trend among foreign investors is clear: they are turning away from speculative assets. Land searches have dropped sharply in favour of income-generating properties with clear legal status and good infrastructure links. It is a maturing market, one that now selects its investors as much as investors select it.
Vietnam 2026: the new Asian giant in your portfolio?
Don't let administrative complexity hold you back. Get a comparative analysis (Vietnam vs Georgia vs Dubai) to check whether this market fits your profile.
The legal framework: what foreigners can and cannot do
This is where Vietnam differs fundamentally from markets such as Dubai or Georgia, where foreigners can buy freehold without major restrictions. In Vietnam, the framework is more complex and must be understood before any commitment.
Foreigners can legally buy apartments and some houses in approved residential projects, but with strict quotas: a maximum of 30% of the units in a residential building and 10% of the houses in a villa project. Direct land ownership is not allowed: all land belongs to the State, and buyers own only the building, with a renewable 50-year lease. There is no golden visa or residency through property investment.
These restrictions are real and it would be dishonest to downplay them. In particular, they mean that secondary-market liquidity for foreigners is more limited than elsewhere. Reselling a property, especially once the 30% quota in a building has been reached, can take time and requires a foreign or local buyer depending on the conditions.
What has changed in recent years is the gradual clarification of the legal framework, which reduces opacity without reaching the transparency of a market such as Singapore or the UAE. Legal due diligence remains essential and non-negotiable.
The trends shaping demand in 2026
International capital is becoming more selective
Ngo Thanh Huan, CEO of FIDT, notes that the global economy is entering an asymmetric phase, with the United States growing strongly while other regions face difficulties. This divergence is pushing capital to reallocate towards markets that combine security and profitability. In this context, Vietnam stands out for the strength of its domestic fundamentals, effective inflation control and a clear economic restructuring strategy.
Investment flows are now shifting from short-term speculative strategies to more selective, long-term approaches. Large planned urban areas with integrated amenities and synchronised infrastructure are becoming the main investment destinations.
ESG as a new selection criterion
Stephen Higgins, Head of Capital Markets at Cushman & Wakefield Japan, points out that investment trends are increasingly tied to ESG criteria. Projects meeting green and sustainable standards should gain a competitive edge in attracting international capital.
This is not an abstract trend. Asian sovereign funds, large European pension funds and institutional family offices starting to look at Vietnam build these criteria into their selection filters. A project without environmental certification or a sustainable management plan will find it increasingly hard to attract quality capital.
What this market is not, and why it matters
Vietnam deserves a clear-eyed reading, not just an enthusiastic one.
Foreign ownership remains constrained by quotas that limit liquidity. There is no residency-by-property-investment scheme, which sets it apart from Dubai, Georgia or Portugal. The local property market, driven by a fast-growing middle class, remains partly disconnected from the foreign segment, which can create pockets of overheating or illiquidity depending on the cycle.
The Vietnamese property market faces two main challenges in 2026: prices already high in some urban areas, and the possibility that interest rates stay high. These factors justify selective caution rather than general enthusiasm.
Compared with Georgia, whose market we follow very closely, Vietnam offers comparable growth potential, even higher in some coastal segments, but with much more restricted access for foreigners, lower liquidity and a legal complexity that requires solid local support. They are two markets with different risk and return profiles, which can fit into complementary wealth strategies depending on the investor's profile.
Conclusion
Vietnam in 2026 is not the easiest market to understand for an international investor. It requires understanding a specific legal framework, accepting ownership constraints other markets do not impose, and working with competent local partners. In return, it offers real economic momentum, solid rental yields in the right segments, and a geographic and geopolitical position that makes it relevant in an international diversification strategy.
For those building a diversified international portfolio, Vietnam deserves serious analysis alongside other markets such as Georgia or Dubai, which it does not replace but can complement depending on each investor's time horizon and objectives. This is the kind of comparative, personalised analysis we carry out with our clients.
Would you like to explore opportunities in Vietnam or compare several international markets?
We help international investors structure their wealth abroad, analysing markets rigorously and without dogma. Book a call with our team.